Another record quarter
As regular readers of the Investment Outlook know, our writing follows the calendar of quarterly earnings reports. The companies that we invest in report financial data and management commentary on a regular basis around the same time each quarter. This is colloquially called “earnings season”. A central component of our investment process is following company-reported financials and management commentary to assess operational progress and future expectations. Internally, we informally declare the “end-of-earnings season” when the results of the Canadian banks are published. In the Canadian banking sector, results remained strong, especially in capital markets and wealth management divisions as markets have been robust and investment banking activity remains high. We also saw generally lower provisions for credit losses with management teams noting that despite the macro volatility around trade, borrowers remain resilient. Despite the strong results, the stock price reaction of banks was mixed, and all of the Big 6, excluding BNS (+5%) and TD (which is relatively flat -0.6%), have had negative performance in the past month as share prices have already risen in anticipation of the strong results.
Regular readers will recognize the aggregate sales data for North American companies noted in Figure 1. We prefer aggregate sales data as it is more difficult to manipulate than earnings. We also focus on “all listed companies” in North America, rather than a widely used index, like the S&P 5oo, because we find the large global companies that dominate those types of indices can skew a significant portion of what would be considered “Main Street”.
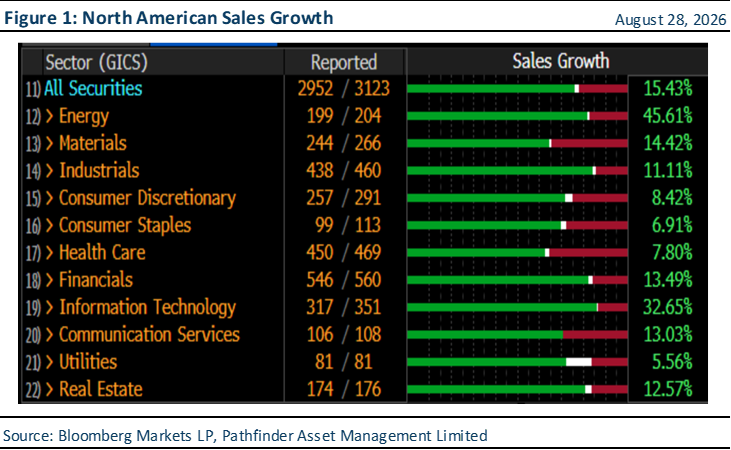
- So far, 2,952 firms or 94.5% of North American companies have reported. The results are the best we’ve seen.
- No sector came close to negative growth. Energy was the strongest (not surprising given the Iran War) and Technology also had another really strong performance.
- We were surprised to see double-digit growth across a wide range of industries. This implies broad growth and ties into the Outlook that we published three weeks ago where we quoted constructive commentary from various managements of “main street” companies.
“This means that” management commentary and the hard data across multiple “real” industries implies a resilient economy defying the headlines. Valuations remain high but the underlying businesses that we own remain strong.
National Instrument 31-103 requires registered firms to disclose information that a reasonable investor would expect to know, including any material conflicts with the firm or its representatives. Doug Johnson and/or Pathfinder Asset Management Limited are an insider of companies periodically mentioned in this report. Please visit www.paml.ca for full disclosures.
Changes in Leverage. We are increasing the asset ceiling to 2.0 times the market value of equity for Pathfinder International Fund and Pathfinder Conviction Fund to be consistent with Pathfinder Partners’ Fund and Pathfinder Resource Fund.
Telephone Call Recording Reminder. To maintain accurate records and support quality service, please note that all telephone calls with our office are recorded, in accordance with applicable privacy laws.
For more information, please follow the links above to review the fund term sheets.
*All returns are time weighted and net of investment management fees. Returns from the Pathfinder Partners’ Fund and Pathfinder Conviction Fund are presented based on the master’s series of each fund. The Pathfinder North American Equity Portfolio and The Pathfinder North American Income Portfolio are live accounts. These are actual accounts owned by the Pathfinder Chairman (Equity) and client (High Income) which contain no legacy positions, cash flows or other Pathfinder investment mandates or products. Monthly inception dates for each fund and portfolio are as follows: Pathfinder North American Equity Portfolio (January 2011), Pathfinder North American High-Income Portfolio (October 2012) Pathfinder Partners’ Fund (April 2011), Pathfinder Conviction Fund (April 2013), and Pathfinder International Fund (November 2014).
Pathfinder Asset Management Limited (PAML) and its affiliates may collectively beneficially own in excess of 10% of one or more classes of the issued and outstanding equity securities mentioned in this newsletter. This publication is intended only to convey information. It is not to be construed as an investment guide or as an offer or solicitation of an offer to buy or sell any of the securities mentioned in it. The author has taken all usual and reasonable precautions to determine that the information contained in this publication has been obtained from sources believed to be reliable and that the procedures used to summarize and analyze such information are based on approved practices and principles in the investment industry. However, the market forces underlying investment value are subject to sudden and dramatic changes and data availability varies from one moment to the next. Consequently, neither the author nor PAML can make any warranty as to the accuracy or completeness of information, analysis or views contained in this publication or their usefulness or suitability in any particular circumstance. You should not undertake any investment or portfolio assessment or other transaction on the basis of this publication, but should first consult your portfolio manager, who can assess all relevant particulars of any proposed investment or transaction. PAML and the author accept no liability of any kind whatsoever or any damages or losses incurred by you as a result of reliance upon or use of this publication.