What's Going on with Banks?
Canadian bank stocks have been some of the best performing securities in the market recently. For the one-year period ending July 31st, 2026, the S&P/TSX Composite Bank Total Return Index rose 69.5% vs the S&P/TSX Composite Total Return Index return of 32.3%
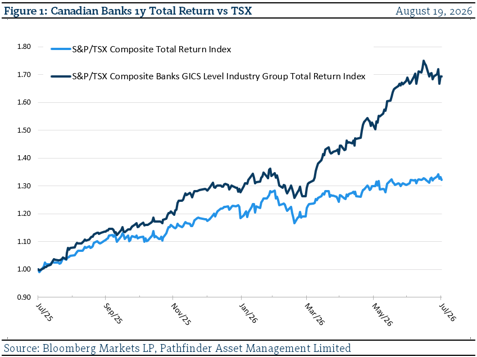
Canadian banks operate in a unique position. The big 6 banks, being RBC, TD, BMO, Scotiabank, CIBC, and National Bank are entrenched players with long histories, built out branch networks, and favorable regulatory hurdles discouraging competition. The strength and scale in the lending business can be leveraged to gain strong positions in other businesses such as wealth management and capital markets which the bank can grow faster with less investment. So, what has been the drivers of strength?
Wealth Management: Banks offer wealth management services to their clients and charge a fee as a percentage of assets. A large percentage of these assets are invested in equities which allows the banks to participate in stronger markets such as those of the past few years with little incremental cost. Additionally, the banks benefit from the existing relationships with clients where they can use their branch relationships to sell wealth management services.
Capital Markets: This is a business where banks offer advisory services to corporations for raising capital as well as trading services to institutions. In periods of active growth and a favorable regulatory environment, banks benefit from the financing of the build out by underwriting debt and equity issuances, and advisory services on acquisitions. As rates have come down and equity markets have risen, we’ve seen an increase in capital markets activity leading to strong results.
“This means that” Canadian banks have posted strong results, which along with improved market sentiment, has resulted in significant share price appreciation. We continue to be focused on the fundamentals of the businesses we own which are high quality, however, remain mindful of valuation.
National Instrument 31-103 requires registered firms to disclose information that a reasonable investor would expect to know, including any material conflicts with the firm or its representatives. Doug Johnson and/or Pathfinder Asset Management Limited are an insider of companies periodically mentioned in this report. Please visit www.paml.ca for full disclosures.
Changes in Leverage. We are increasing the asset ceiling to 2.0 times the market value of equity for Pathfinder International Fund and Pathfinder Conviction Fund to be consistent with Pathfinder Partners’ Fund and Pathfinder Resource Fund.
Telephone Call Recording Reminder. To maintain accurate records and support quality service, please note that all telephone calls with our office are recorded, in accordance with applicable privacy laws.
For more information, please follow the links above to review the fund term sheets.
*All returns are time weighted and net of investment management fees. Returns from the Pathfinder Partners’ Fund and Pathfinder Conviction Fund are presented based on the master’s series of each fund. The Pathfinder North American Equity Portfolio and The Pathfinder North American Income Portfolio are live accounts. These are actual accounts owned by the Pathfinder Chairman (Equity) and client (High Income) which contain no legacy positions, cash flows or other Pathfinder investment mandates or products. Monthly inception dates for each fund and portfolio are as follows: Pathfinder North American Equity Portfolio (January 2011), Pathfinder North American High-Income Portfolio (October 2012) Pathfinder Partners’ Fund (April 2011), Pathfinder Conviction Fund (April 2013), and Pathfinder International Fund (November 2014).
Pathfinder Asset Management Limited (PAML) and its affiliates may collectively beneficially own in excess of 10% of one or more classes of the issued and outstanding equity securities mentioned in this newsletter. This publication is intended only to convey information. It is not to be construed as an investment guide or as an offer or solicitation of an offer to buy or sell any of the securities mentioned in it. The author has taken all usual and reasonable precautions to determine that the information contained in this publication has been obtained from sources believed to be reliable and that the procedures used to summarize and analyze such information are based on approved practices and principles in the investment industry. However, the market forces underlying investment value are subject to sudden and dramatic changes and data availability varies from one moment to the next. Consequently, neither the author nor PAML can make any warranty as to the accuracy or completeness of information, analysis or views contained in this publication or their usefulness or suitability in any particular circumstance. You should not undertake any investment or portfolio assessment or other transaction on the basis of this publication, but should first consult your portfolio manager, who can assess all relevant particulars of any proposed investment or transaction. PAML and the author accept no liability of any kind whatsoever or any damages or losses incurred by you as a result of reliance upon or use of this publication.